Modular Computation Approaches for Aligning Expected Values With Position Sizes in Multi-Event Wagering Portfolios
Written by Felix Flores · Aug 28, 2026
Modular Computation Approaches for Aligning Expected Values With Position Sizes in Multi-Event Wagering Portfolios
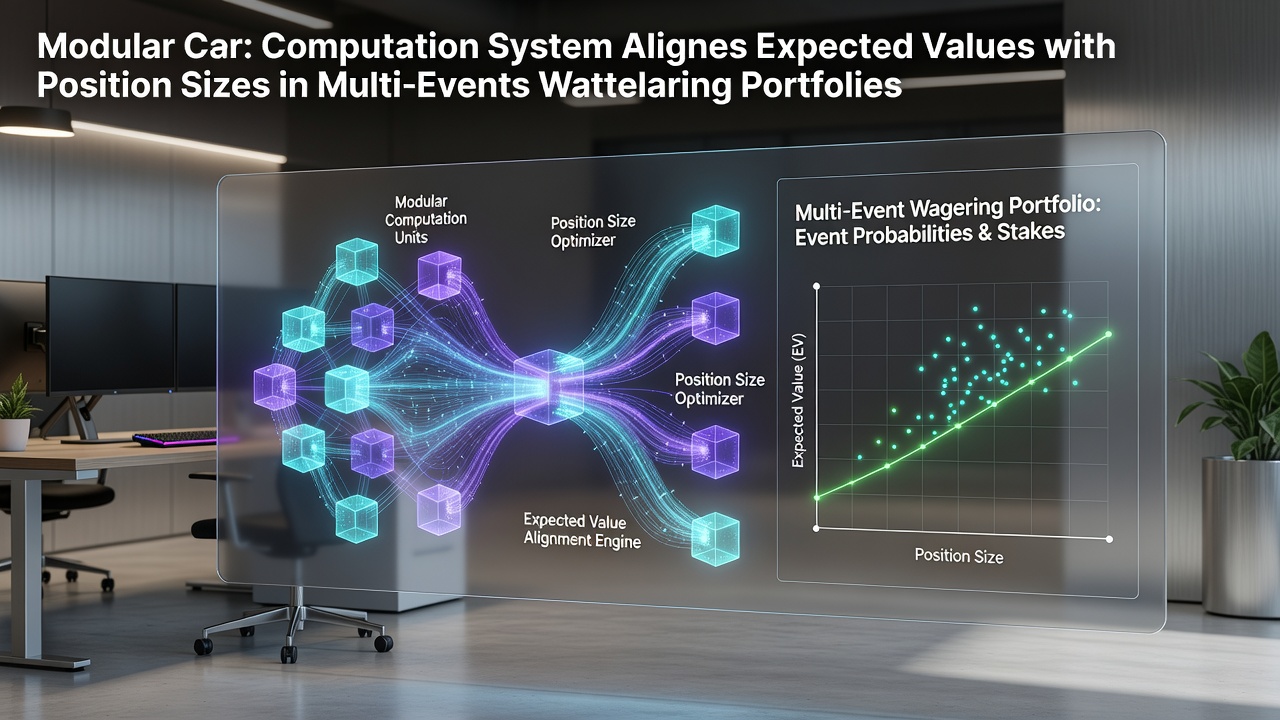
Modular computation systems break down the process of calculating expected values and determining position sizes into separate interchangeable components that handle data inputs, probability assessments, and risk adjustments for portfolios spanning multiple events, and these frameworks allow operators to update individual modules without rebuilding entire platforms as market conditions shift in August 2026.
Core Components of Expected Value Calculation Modules
Expected value modules process odds data alongside probability estimates derived from historical records and real-time inputs, while they apply formulas that subtract implied probabilities from assessed chances to generate positive or negative edges across events such as soccer matches, tennis tournaments, and horse races. Researchers at academic institutions have developed these modules to operate independently so that updates to probability models in one area do not affect stake allocation logic elsewhere in the system.
Position Sizing Algorithms and Portfolio Integration
Position sizing modules receive outputs from expected value calculations and apply allocation rules that account for bankroll totals, event correlations, and variance measures before determining wager amounts, and this separation enables users to swap in different sizing strategies such as fractional Kelly variants or volatility-adjusted methods while maintaining consistency across a portfolio. Data from industry reports indicates that systems using modular designs reduce computational overhead when handling simultaneous events because each module processes its assigned task in sequence or parallel depending on configuration.
Handling Correlations Across Multiple Events
Portfolio-level modules incorporate correlation matrices that adjust position sizes downward when events share underlying factors like weather conditions or team performance trends, and these adjustments prevent overexposure that could occur if independent sizing were applied to each wager. Observers note that modular architectures make it straightforward to integrate external data feeds for correlation estimates since the relevant module can be modified or replaced without disrupting value computation or basic sizing functions.
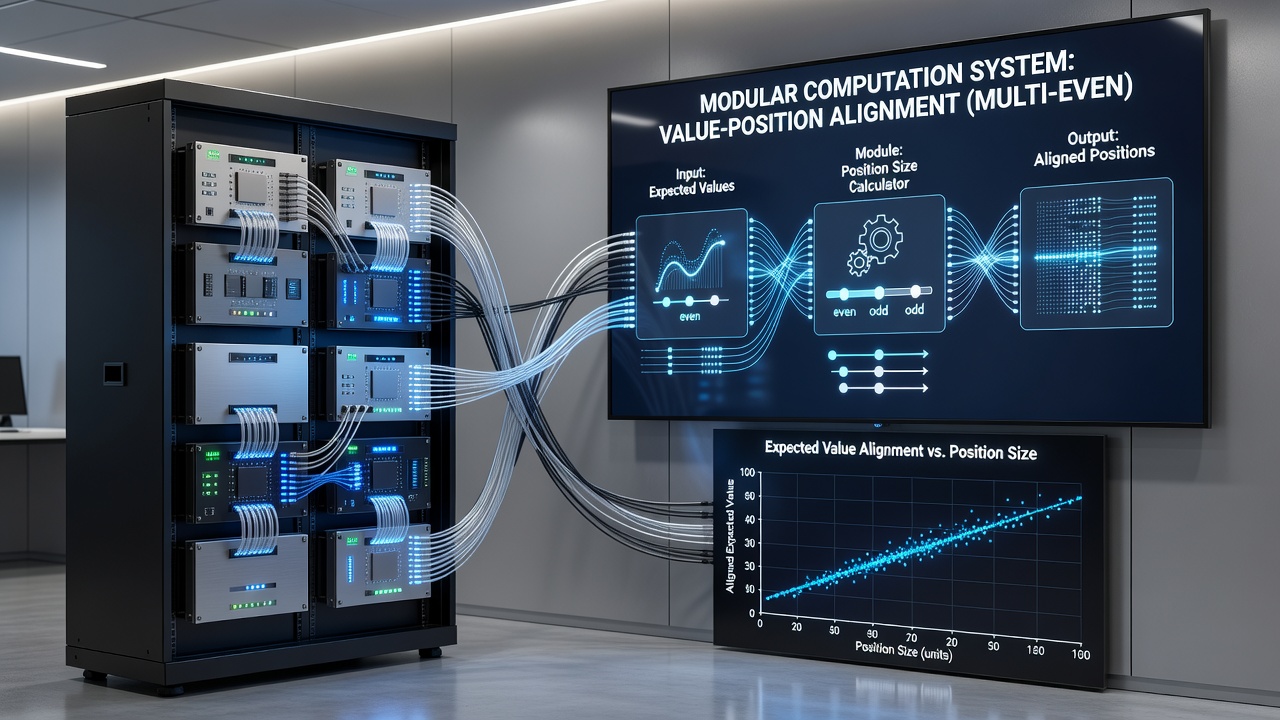
One study revealed that integrated systems using separate correlation handling achieved more stable returns over time compared with non-modular setups because adjustments happen at the portfolio layer rather than inside individual event calculations.
Implementation in August 2026 Market Conditions
As of August 2026 several wagering platforms have adopted modular designs to respond quickly to regulatory changes affecting stake limits in certain jurisdictions, and the architecture allows operators to isolate and update compliance modules while leaving expected value and sizing components intact. Figures from the American Gaming Association show increased interest in scalable computation tools that support multi-event management across international markets.
Advantages of Modular Over Monolithic Systems
Modular setups permit testing of new probability models or sizing rules on isolated components before full deployment, whereas monolithic programs require complete revalidation for any change, and this difference leads to faster iteration cycles according to developers who have compared both approaches in controlled environments. People who maintain these systems report that troubleshooting becomes more targeted since errors surface within specific modules rather than across an entire codebase.
Case Examples From Operational Use
There's this case where a European betting operator integrated a dedicated variance module that recalculated position sizes after each event outcome and maintained portfolio exposure within predefined bands during a period of high market volatility. Another implementation at an Australian research-backed platform demonstrated how swapping an expected value module for one using machine learning outputs improved alignment between calculated edges and final stake decisions without altering the downstream sizing logic.
Future Directions in Computation Design
Developers continue to explore ways to add reinforcement learning modules that refine both value estimates and sizing rules based on historical portfolio performance, while maintaining the separation of concerns that defines modular architecture. Reports from the Victorian Responsible Gambling Foundation highlight ongoing work to ensure these systems include safeguards that flag when automated sizing recommendations exceed operator-defined risk thresholds.
Conclusion
Modular computation systems provide a structured method for connecting expected value outputs directly to position sizing decisions across diverse event portfolios by isolating functions into replaceable components, and this design supports ongoing adaptation as data sources and market conditions evolve through 2026 and beyond. Evidence from operational deployments shows that the approach delivers consistent handling of correlations and risk parameters while allowing targeted updates to individual calculation stages.